Understanding the Risks of 72- and 84-Month Car Loans for Service Members
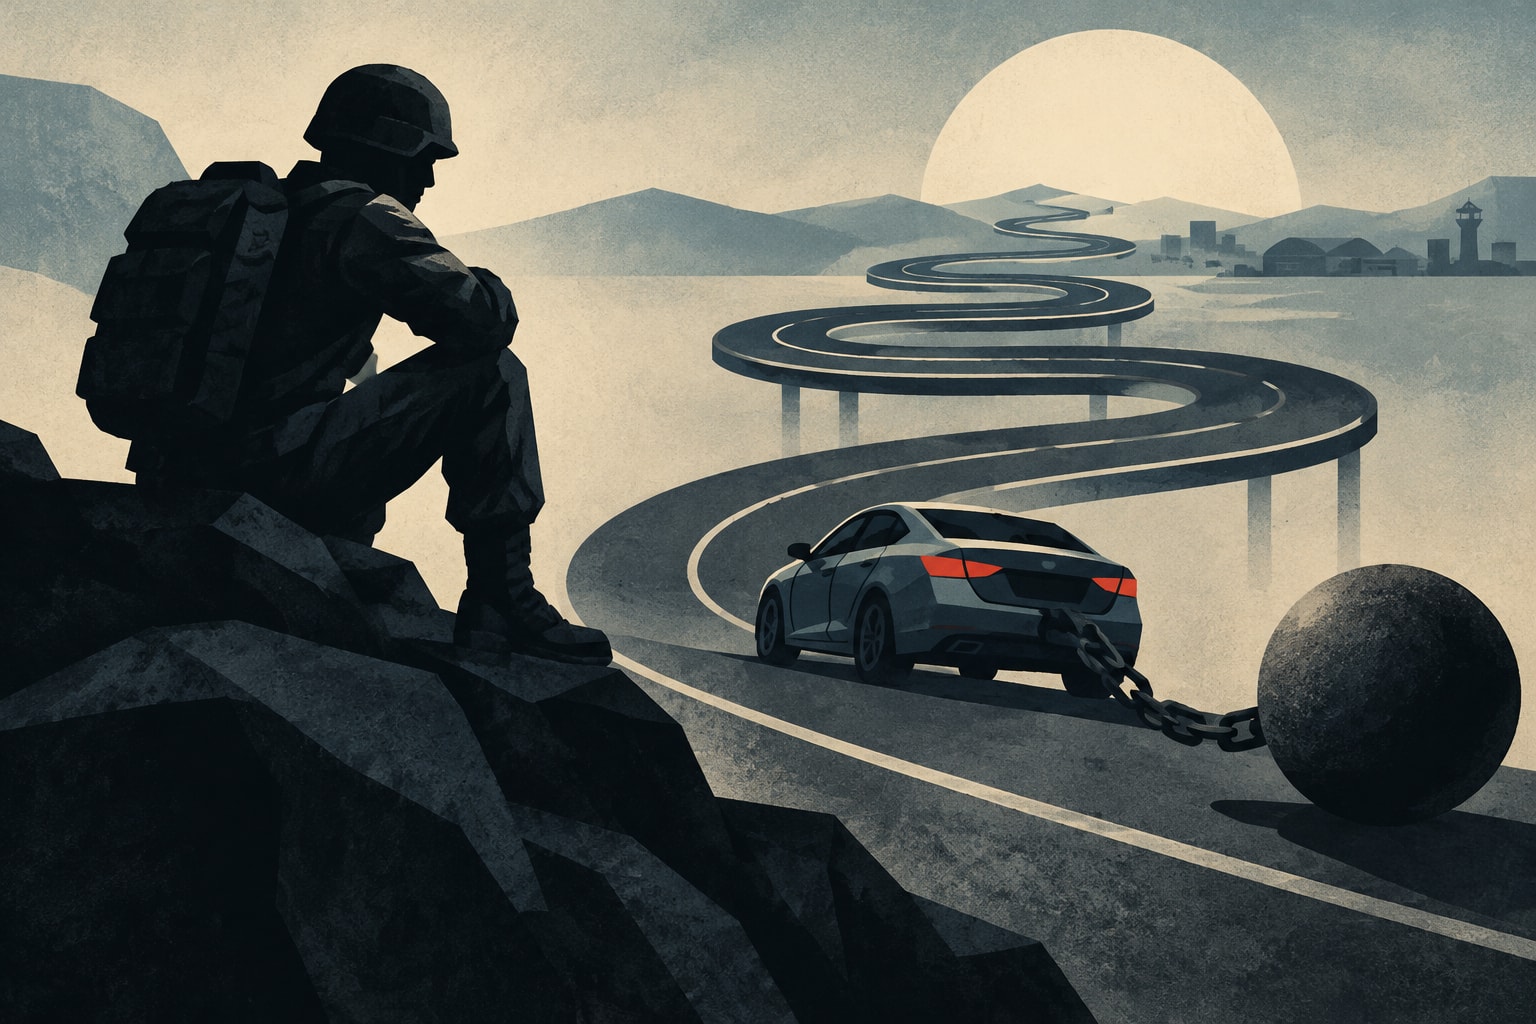
Long-term car loans can pose unique financial risks for military personnel, especially during moves and with vehicle depreciation.
What's Happening
- •Service members are increasingly considering 72- and 84-month car loans.
- •These loans can lead to negative equity due to vehicle depreciation.
- •PCS moves can complicate long-term loan commitments.
Why It Matters
Service members often face unique financial challenges due to frequent relocations and the unpredictable nature of military life. Understanding the risks associated with long-term car loans is essential for maintaining financial stability and avoiding potential pitfalls that could lead to debt or financial strain.
What Changes Now
- •Service members may need to reconsider their financing options for vehicle purchases. This includes evaluating the risks of long-term loans versus potential benefits of shorter terms or leasing.
- •Financial education resources may become more critical for military personnel. Institutions may need to offer tailored advice to help service members navigate these decisions effectively.
- •Awareness of vehicle depreciation should be prioritized among service members. Understanding how quickly vehicles lose value can inform better purchasing decisions.
What to Watch
- •Monitor changes in auto loan interest rates. Fluctuations can affect the overall cost of long-term loans, making it essential to stay informed.
- •Keep an eye on financial education programs offered by military installations. These programs may provide valuable insights into managing loans and budgeting.
- •Watch for updates on policies related to PCS moves and vehicle financing. Changes could impact how service members manage their loans during relocations.
Get the Daily Briefing
Military and veteran news that actually affects you, in your inbox each morning.
More Context
- •The Appeal of Long-Term Loans: Long-term car loans, such as those extending to 72 or 84 months, may seem attractive due to lower monthly payments. For many service members, especially those in the E-4 to E-6 rank range, these lower payments can help manage tight budgets, particularly during deployments or while stationed at a new duty station. However, the allure of affordability can mask significant financial risks, particularly as vehicles lose value over time.
- •Understanding Depreciation: Vehicles typically depreciate quickly, often losing 20% of their value within the first year of ownership. For service members who take out long-term loans, this rapid depreciation can lead to a situation where they owe more on the loan than the vehicle is worth, known as being 'upside down' on the loan. This situation can be exacerbated by the frequent moves associated with military life, making it difficult to sell or trade in the vehicle without incurring a loss.
- •Impact of Permanent Change of Station (PCS): PCS orders can further complicate long-term car loans, as service members may need to relocate before the loan is paid off. This can lead to challenges in selling the vehicle or transferring the loan, potentially resulting in financial strain. Understanding the terms of the loan and the implications of a PCS is crucial for service members to avoid financial pitfalls during their military careers.
- •Practical Steps for Service Members: Before committing to a long-term car loan, service members should assess their financial situation carefully. It is advisable to calculate the total cost of the loan, including interest, and consider how long they plan to keep the vehicle. Additionally, exploring shorter loan terms or leasing options may provide more flexibility, especially for those who anticipate frequent relocations.
Frequently Asked Questions
Are long-term car loans a good idea for service members?
Long-term car loans can be risky due to rapid vehicle depreciation and the potential for being upside down on the loan, especially during PCS moves.
What should I consider before taking a 72-month car loan?
Consider the total cost of the loan, including interest, and how long you plan to keep the vehicle to avoid financial strain.
How does a PCS affect my car loan?
A PCS can complicate your car loan situation, making it difficult to sell or transfer the loan, which may lead to financial loss.
The Daily Briefing
Military & veteran news that actually affects you — delivered every morning.
- Pay, benefits & policy changes
- Pentagon decisions that matter
- VA updates for veterans & families
- One email. No spam. Unsubscribe anytime.
Related Stories
- Navigating Your Car Options Before a PCS Move— Military.com
- Understanding Homeowners Insurance Vacancy Rules During PCS and Deployment— Military.com
- NASA Accelerates Plans for Moon Base and Astronaut Missions— Military.com
- Oshkosh Begins Production of Dutch Military Patrol Vehicle Prototype— Defense News